Each week we will offer a very brief market update to help keep you informed on the latest. Want the latest delivered right to your email? Click HERE to provide your email address.
Week of October 26th Recap
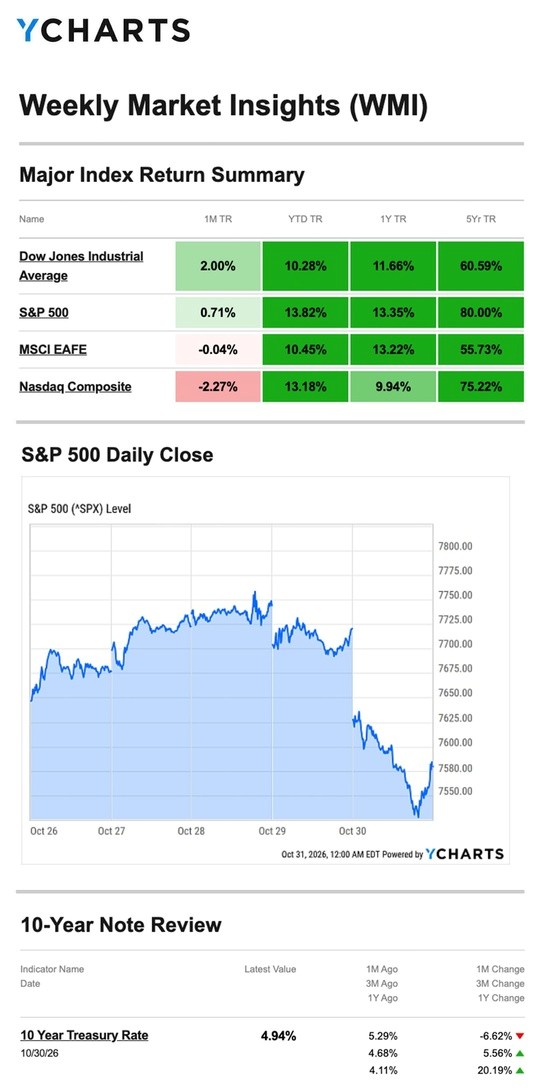
Stocks ended last week lower as disappointing Q3 corporate reports led to a tech-led selloff that deepened on Friday.
The Standard & Poor’s 500 Index slipped 0.57 percent, while the Nasdaq Composite Index declined 2.00 percent. The Dow Jones Industrial Average fell 0.85 percent. The MSCI EAFE Index, which tracks developed overseas stock markets, rose 0.85 percent.1,2
Early Enthusiasm
The AI trade got a fresh boost to kick off the week as one of the largest AI platforms filed for an initial public offering. Investors also appeared upbeat about one of the biggest weeks for Q3 corporate earnings results.
Monday’s momentum extended into Tuesday’s session, while falling oil prices over both days added to investor enthusiasm.3
Then midweek, the Fed held rates steady as expected, which was met with mixed trading. But all three averages closed modestly higher on Wednesday. Over the first three days of the week, the Nasdaq rose more than 2 percent and the S&P 500 added more than 1½ percent.4
Thursday’s session opened on a down note following mixed Q3 corporate results from two of the largest tech giants. Despite a stronger-than-expected gross domestic product (GDP) report and the fact that seven out of the 11 S&P 500 sectors advanced, stocks remained under pressure throughout the day.5
Then Friday, the tech-led selloff deepened as traders appeared to favor more defensive sectors as the month closed out. The Nasdaq declined nearly 3 percent over the session.6
Upbeat Q3 GDP Report
The Fed’s decision last Wednesday to keep short-term interest rates unchanged was expected. But two Fed officials voted for raising rates, which was a bit of a surprise.7
Another surprise last week was news that the economy grew 3.4 percent in Q3, according to the Commerce Department’s initial estimate. That beat economists’ expectations of 3.1 percent growth but, more importantly, marked an acceleration from Q2, when GDP grew 2.2 percent.8
This Week: Key Economic Data
Monday: Purchasing Managers Index (PMI)—Manufacturing. Construction Spending.
Tuesday: Job Openings & Labor Turnover. Factory Orders.
Wednesday: ADP National Employment Report (private sector). Trade Balance. PMI—Services.
Thursday: Productivity and Costs. Weekly Jobless Claims.
Friday: Employment Report. U. Michigan Consumer Survey. Consumer Credit.
Source: Investor’s Business Daily – Econoday economic calendar: October 30, 2026. The Econoday economic calendar lists upcoming U.S. economic data releases (including key economic indicators), Federal Reserve policy meetings, and speaking engagements of Federal Reserve officials. The content is developed from sources believed to provide accurate information. The forecasts or forward-looking statements are based on assumptions and may not materialize. The forecasts are also subject to revision.
Week of October 19th Recap
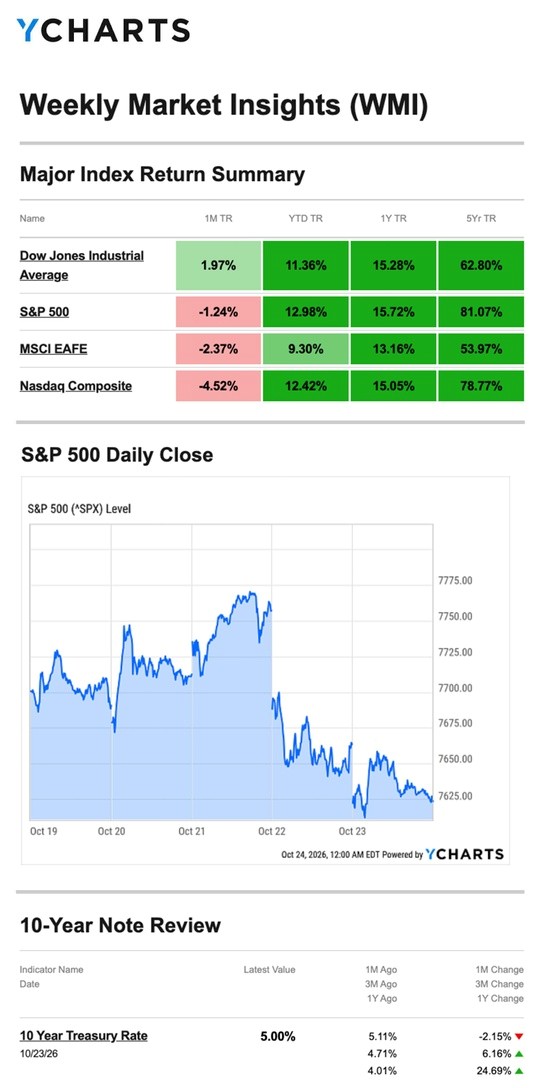
Markets were mixed last week, though persistent pressure on technology stocks made the week feel more challenging for some investors.
The Standard & Poor’s 500 Index lost 0.47 percent, while the Nasdaq Composite Index declined 0.71 percent. The Dow Jones Industrial Average gained 0.41 percent. The MSCI EAFE Index, which tracks developed overseas stock markets, fell 1.58 percent.1,2
Tech Leads Both Ways
The week began with an AI-led rebound as investors looked ahead to a heavy slate of corporate earnings reports. On Tuesday, investors cheered the first wave of corporate results and falling oil prices, which helped boost investor sentiment.
Tech swung back into favor midweek as investors applauded reports that two of the largest megacap tech firms formed a committee to evaluate a potential merger, lifting all three averages. The Nasdaq gained more than 1 percent, while the S&P posted its third straight winning close.3,4
Boomerang Effect
But the boomerang started to come back on Thursday as AI debt worries returned while oil prices rose again amid fresh geopolitical concerns. The Nasdaq slid more than 2½ percent over the session, while the S&P fell more than 1 percent, posting their steepest daily declines since June and July, respectively.5
The week wrapped up with technology stocks again in the spotlight due to persistent AI-related worries. The Dow closed Friday down more than 1 percent, while the S&P 500 and Nasdaq were under pressure into the close.6
Housing Watch
With everything going on last week, the housing market didn’t get much coverage. But there were some important housing developments.
First, housing starts fell 5.2 percent in September over the prior month, below expectations for a 2 percent rise. It was the second straight month when economists expected starts to rise, and instead they fell, and the third consecutive month of declines.7
Meanwhile, pending home sales fell to their lowest level on record in September in part due to an increase in mortgage rates.8
This Week: Key Economic Data
Tuesday: Durable Goods. S&P Cotality Case-Shiller Home Price Index. New Home Sales. Consumer Confidence (Conference Board). Federal Open Market Committee (FOMC) Meeting, Day 1.
Wednesday: Trade Balance in Goods. Wholesale Inventories. Retail Inventories. FOMC Meeting, Day 2 / Fed Interest Rate Decision.
Thursday: Gross Domestic Product (GDP). Weekly Jobless Claims. Personal Consumption Expenditures (PCE) Index.
Friday: Employment Cost Index.
Source: Investor’s Business Daily – Econoday economic calendar: October 23, 2026. The Econoday economic calendar lists upcoming U.S. economic data releases (including key economic indicators), Federal Reserve policy meetings, and speaking engagements of Federal Reserve officials. The content is developed from sources believed to provide accurate information. The forecasts or forward-looking statements are based on assumptions and may not materialize. The forecasts are also subject to revision.
Week of October 12th Recap
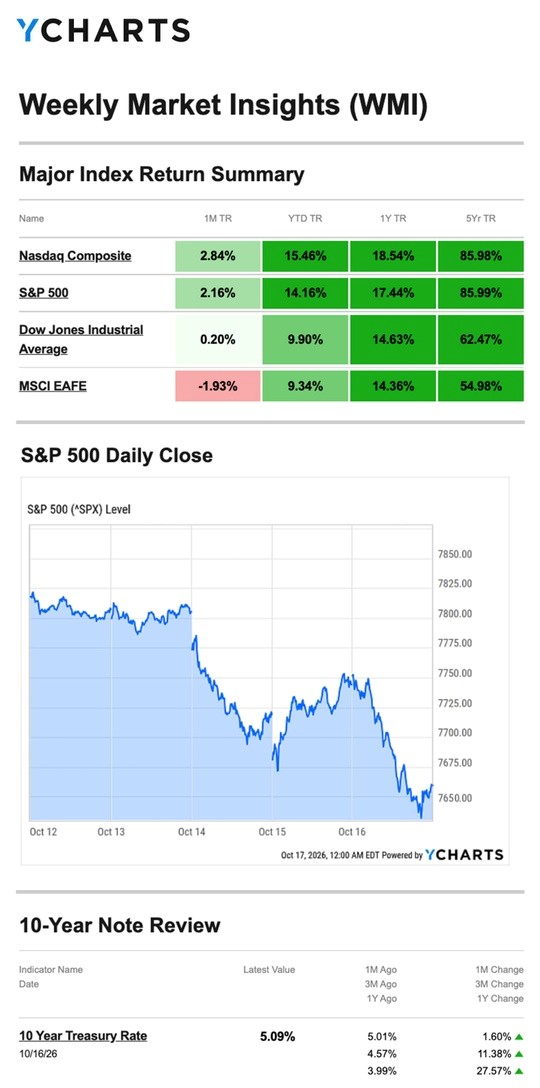
Stocks were under pressure last week as corporate earnings results, rising oil prices, and AI valuation anxieties unsettled investors.
The Standard & Poor’s 500 Index lost 1.95 percent, while the Nasdaq Composite Index declined 4.48 percent. By contrast, the Dow Jones Industrial Average gained 0.67 percent. The MSCI EAFE Index, which tracks developed overseas stock markets, rose 0.96 percent.1,2
Tough Week for Tech
Markets traded in a tight range over the first two days of the week as investors awaited a slew of Q3 corporate earnings results, mostly from big financial services companies, later in the week. That first batch of earnings announcements came in Tuesday, with mostly strong results, but high investor expectations kept markets from moving much.3
Then midweek, investors appeared to rotate out of AI names as they digested a warm retail inflation report. Those two factors shifted sentiment, and stocks trended lower. However, the Dow Industrials proved more defensive, ending the session essentially flat.4
On Thursday, AI stocks were under pressure again as investors appeared to favor more value-oriented names.5
As the week wrapped up, oil prices rose to their highest level since May, while sellers targeted AI- and tech-related names. The Nasdaq found some support at the close but still had its worst week since June.6
Inflation Jitters
Fresh retail and wholesale inflation reports were out last week. Both came in hotter than expected, which put the spotlight on the Fed’s meeting in late October.
The Consumer Price Index report, out Wednesday, showed inflation rose 3.7 percent in September, higher than the 3.6 percent economists expected. And Thursday’s Producer Price Index report showed wholesale inflation hit 6.6 percent year over year—the highest level in four years.7,8
This Week: Key Economic Data
Monday: NAHB Housing Market Index.
Tuesday: Housing Starts. Pending Home Sales.
Thursday: Weekly Jobless Claims. Leading Indicators. Kansas City Fed Survey.
Friday: Purchasing Managers’ Index (PMI)—Manufacturing. PMI—Services. U. Michigan Consumer Sentiment Survey (final).
Source: Investor’s Business Daily – Econoday economic calendar: October 16, 2026. The Econoday economic calendar lists upcoming U.S. economic data releases (including key economic indicators), Federal Reserve policy meetings, and speaking engagements of Federal Reserve officials. The content is developed from sources believed to provide accurate information. The forecasts or forward-looking statements are based on assumptions and may not materialize. The forecasts are also subject to revision.
Week of October 5th Recap
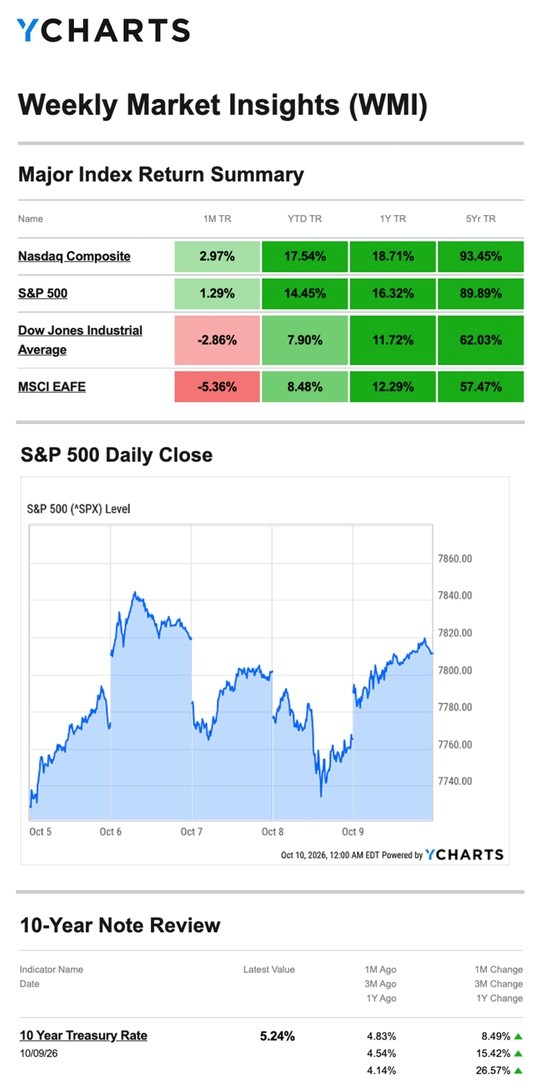
Stocks ended last week higher after an up-and-down week where a kitchen sink of economic, geopolitical, and AI-related events competed for investors’ attention.
The Standard & Poor’s 500 Index rose 1.15 percent, while the Nasdaq Composite Index advanced 0.64 percent. The Dow Jones Industrial Average gained 0.93 percent. The MSCI EAFE Index, which tracks developed overseas stock markets, fell 0.45 percent.1,2
A Choppy Advance
Stocks opened higher to start the week, demonstrating continued resilience despite rising Treasury yields. Stocks continued their climb on Tuesday as cooler yields prevailed and oil prices treaded water. AI chipmakers led the broad market higher, with the S&P 500 closing above 7,800 for the first time and the Nasdaq also notching a record close.3,4
Then markets stumbled midweek, opening lower on Wednesday after Treasury yields hit fresh multidecade highs. However, stocks rebounded after an encouraging 10-year Treasury auction appeared to allay some fears, with the S&P 500 and the Nasdaq reversing the lion’s share of declines by the closing bell.5
Jitters crept back into market sentiment as stocks opened lower Thursday. The Nasdaq closed down nearly 1½ percent, its biggest one-day decline since mid-August.6
Stocks rebounded Friday to finish the week strong, with megacap tech stocks rallying and oil prices falling on news of a deal to supply diesel to U.S. and global markets. Healthcare stocks also contributed to the gains as the Nasdaq logged its fourth consecutive weekly gain.7
As the Fed Turns
Three things happened on Wednesday that made the Federal Reserve’s job a bit more complex as it weighs its decision on interest rates at its next meeting later this month.
Yields on both the bellwether 10-year Treasury note and the 30-year Treasury bond hit new 24-year highs, which contributed to mortgage rates reaching a near-three-year high. However, a well-received auction of 10-year Treasury notes seemed to suggest that buyers believed yields would eventually fall again.8
This Week: Key Economic Data
Tuesday: NFIB Small Business Optimism Index. Existing Home Sales. Monthly Treasury Statement and Outlays.
Wednesday: Consumer Price Index (CPI). Federal Reserve Beige Book.
Thursday: Weekly Jobless Claims. Producer Price Index (PPI). Manufacturing & Trade Inventories. Cleveland Fed President Beth Hammack speaks.
Friday: Import Prices. Industrial Production. Capacity Utilization.
Source: Investor’s Business Daily – Econoday economic calendar: October 9, 2026. The Econoday economic calendar lists upcoming U.S. economic data releases (including key economic indicators), Federal Reserve policy meetings, and speaking engagements of Federal Reserve officials. The content is developed from sources believed to provide accurate information. The forecasts or forward-looking statements are based on assumptions and may not materialize. The forecasts are also subject to revision.
Week of September 28th Recap
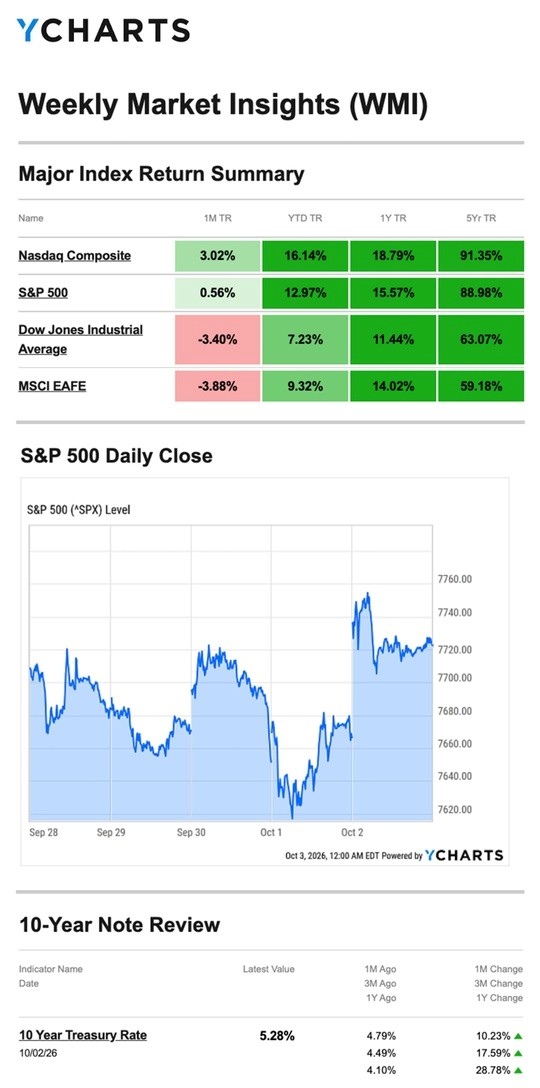
Stocks ended last week mixed as a tug-of-war between strong economic data, cooler job growth, and decades-high Treasury yields played out.
The Standard & Poor’s 500 Index edged down 0.27 percent, while the Nasdaq Composite Index rose 0.45 percent. The Dow Jones Industrial Average slid 1.26 percent. The MSCI EAFE Index, which tracks developed overseas stock markets, fell 1.81 percent.1,2
A Mixed Week
Stocks fell at the start of the week as Treasury yields continued to rise. They steadied over the next session with Treasury yields still in the spotlight. The benchmark 10-year Treasury yield topped 5.29 percent, up 133 basis points from its year-to-date low in late February.3,4
Markets perked up midweek after a revision to Q2 GDP showed the economy grew faster than originally estimated. Quarterly earnings results for a large semiconductor also supported markets, while rising oil prices kept enthusiasm in check.5,6
After a soft jobs report, stocks opened higher on Friday, with investors wondering whether the Fed would adjust rates at the end of the month. The AI trade roused once again to lead the Nasdaq to a fresh intraday record and end the week on a high note.7
Contrasting Economic Data
Q2 GDP was revised upward from 1.5 percent to 2.2 percent, flipping the economy’s trajectory over the first half of the year from slowing to growing.8
On the other hand, the latest jobs report showed job growth slowed in September to 29,000 jobs added, a falloff from August’s downwardly revised 133,000 job gain (from 162,000). Jobs added in July were also revised down, reflecting a total well under 200,000 for Q3.9
Also in the mix was last week’s Personal Consumption Expenditures (PCE) Index report, which showed inflation held steady in August at 3.4 percent over the prior 12 months. The Fed’s long-standing target has been 2 percent inflation.8
This Week: Key Economic Data
Monday: Purchasing Managers Index (PMI)—Services.
Tuesday: Trade Balance. Dallas Fed President Lorie Logan speaks.
Wednesday: Federal Open Market Committee (FOMC) Meeting Minutes. Consumer Credit.
Thursday: Weekly Jobless Claims. Monthly Wholesale Trade.
Friday: Consumer Sentiment (U. Michigan Survey). Kansas City Fed President Jeffrey Schmid speaks.
Source: Investor’s Business Daily – Econoday economic calendar: October 2, 2026.
The Econoday economic calendar lists upcoming U.S. economic data releases (including key economic indicators), Federal Reserve policy meetings, and speaking engagements of Federal Reserve officials. The content is developed from sources believed to provide accurate information. The forecasts or forward-looking statements are based on assumptions and may not materialize. The forecasts are also subject to revision.
Week of September 21st Recap
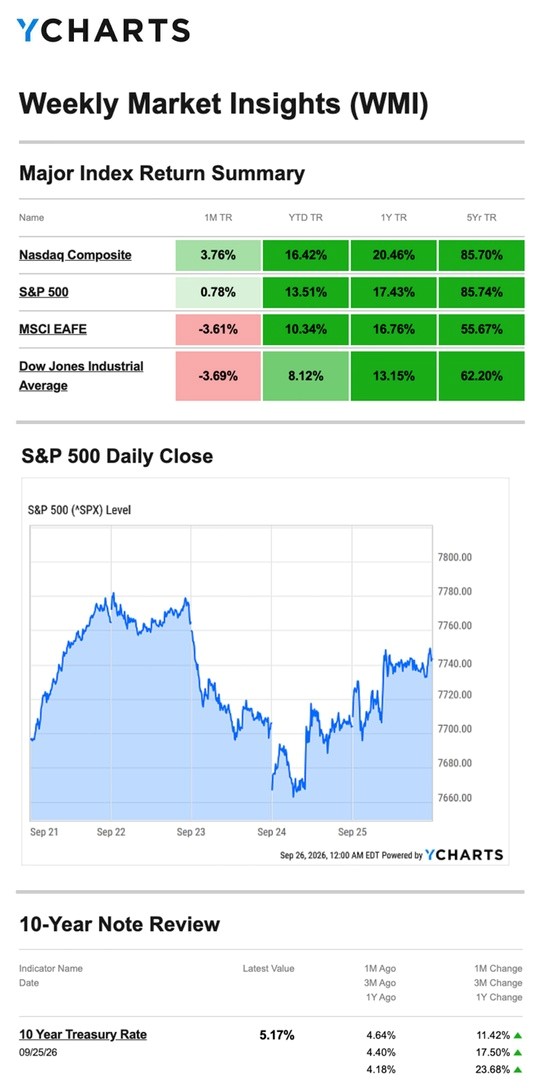
Stocks advanced last week as the broad market looked past inflationary pressures and focused on falling oil prices, declining bond yields, and ongoing diplomatic efforts in the Middle East.
The Standard & Poor’s 500 Index rose 1.22 percent, while the Nasdaq Composite Index advanced 2.06 percent. The Dow Jones Industrial Average edged up 0.28 percent. The MSCI EAFE Index, which tracks developed overseas stock markets, added 0.15 percent.1,2
Choppy Trading
Stocks bolted out of the gate to start the week, rebounding thanks to AI stocks, falling oil prices, and bond yields. The Nasdaq hit a record intraday high during Monday’s session.
The broad market went sideways on Tuesday as traders kept an eye on developments in the Middle East, while oil prices and Treasury yields slid further.3,4
Markets then fell midweek amid investor concerns over comments from one Fed official and two inflation updates. All three major averages were under pressure. The malaise hung on into Thursday, but stocks began to climb late in the day on upbeat reports out of the Middle East.5,6
All three major averages continued their recovery Friday, ending the day with some momentum going into the close.7
Eyes on Bonds
Treasury yields hit multidecade highs last week due to a couple of factors.
The first was Federal Reserve Governor Michael Barr’s hawkish language on Wednesday, suggesting he was open to another rate adjustment at the October Fed meeting. And the second was the Purchasing Managers’ Index (PMI) reports for both manufacturing and services, which were also released on Wednesday. Both reports showed costs hit four-year highs for the month.8
This Week: Key Economic Data
Tuesday: S&P Cotality Case-Shiller Home Price Index. Consumer Confidence. Job Openings & Labor Turnover. Fed speeches: Austan Goolsbee (Chicago) & John Williams (NYC).
Wednesday: ADP Employment Report (private sector). Gross Domestic Product (GDP), Q2 (third estimate). Trade Balance in Goods. Wholesale & Retail Inventories. Personal Consumption Expenditures (PCE) Index. Fed President Goolsbee speaks.
Thursday: Weekly Jobless Claims. Purchasing Managers Index (PMI)—Manufacturing. Construction Spending.
Friday: Employment Report. Factory Orders.
Source: Investor’s Business Daily – Econoday economic calendar: September 25, 2026. The Econoday economic calendar lists upcoming U.S. economic data releases (including key economic indicators), Federal Reserve policy meetings, and speaking engagements of Federal Reserve officials. The content is developed from sources believed to provide accurate information. The forecasts or forward-looking statements are based on assumptions and may not materialize. The forecasts are also subject to revision.
Week of September 14th Recap
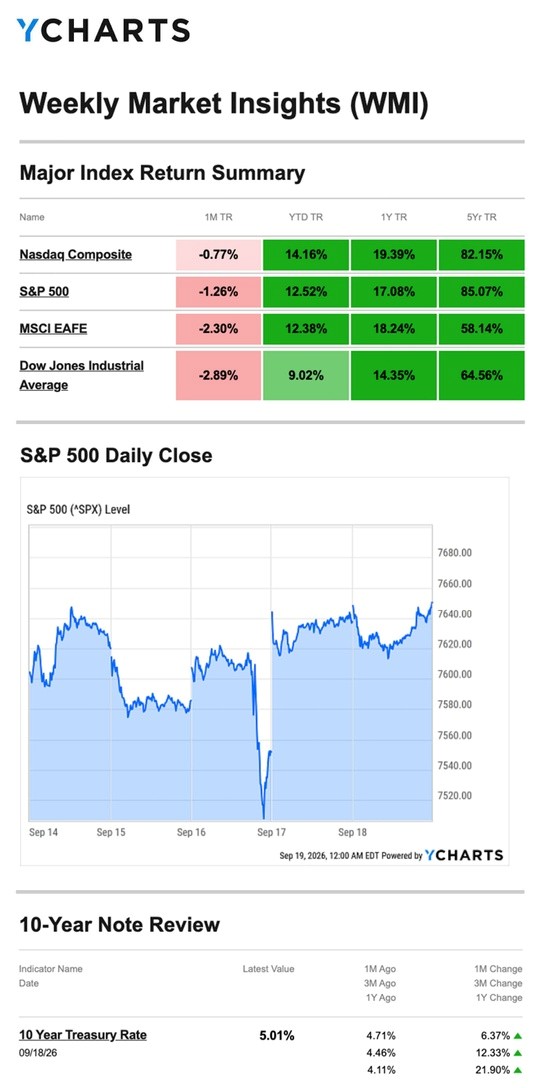
Stocks ended last week mixed as investors navigated the Fed’s rate decision, Treasury yields, oil prices, and the volatile AI trade.
The Standard & Poor’s 500 Index declined 0.09 percent, while the Nasdaq Composite Index rose 0.72 percent. The Dow Jones Industrial Average fell 1.70 percent. The MSCI EAFE Index, which tracks developed overseas stock markets, skidded 1.32 percent.1,2
Mixed Markets
Stocks opened lower to start the week as safety concerns tempered the artificial intelligence trade and oil prices rose. Markets slid again over the next session as the bellwether 10-year Treasury yield rose above 5 percent to a 19-year high.3,4
Markets steadied midweek as investors awaited the Fed’s decision on the final day of its September meeting. The Fed raised short-term interest rates by a quarter percentage point in a widely anticipated decision, reflecting inflation concerns. Stocks fell following the decision, but declines in the broader market were modest.5
Stocks rebounded Thursday, clawing back some losses from the prior session. Lower oil prices, falling Treasury yields, and advances in a handful of megacap tech stocks helped lift all three major market averages. But the relief rally stalled out a bit on Friday morning as Treasury yields rose again.6,7
Focus on the Fed
The Federal Open Market Committee voted unanimously to raise interest rates, increasing the Fed Funds rate by a quarter percentage point to a target range of 3¾ to 4 percent. Of the 18 officials who submitted medium-term projections for the Fed’s so-called “dot-plot,” 16 penciled in at least one more adjustment this year. (The FOMC meets twice more before year-end.)8
In his post-meeting press conference, Fed Chair Kevin Warsh said that “inflation is too high and has been for too long.” He added that despite expanding economic activity, “uncertainty remains elevated, owing in part to geopolitical developments,” and that the Fed’s decision supports a “timelier return” to its goal of 2 percent inflation.8,9
This Week: Key Economic Data
Tuesday: Richmond Fed President Tom Barkin speaks.
Wednesday: Purchasing Managers Index (PMI)—Manufacturing. Purchasing Managers Index (PMI)—Services.
Thursday: Weekly Jobless Claims. New Home Sales. Fed President Barkin speaks.
Friday: Durable Goods. U. Michigan Consumer Sentiment Survey.
Source: Investors Business Daily – Econoday economic calendar; September 18, 2026. The Econoday economic calendar lists upcoming U.S. economic data releases (including key economic indicators), Federal Reserve policy meetings, and speaking engagements of Federal Reserve officials. The content is developed from sources believed to provide accurate information. The forecasts or forward-looking statements are based on assumptions and may not materialize. The forecasts are also subject to revision.
Week of September 7th Recap
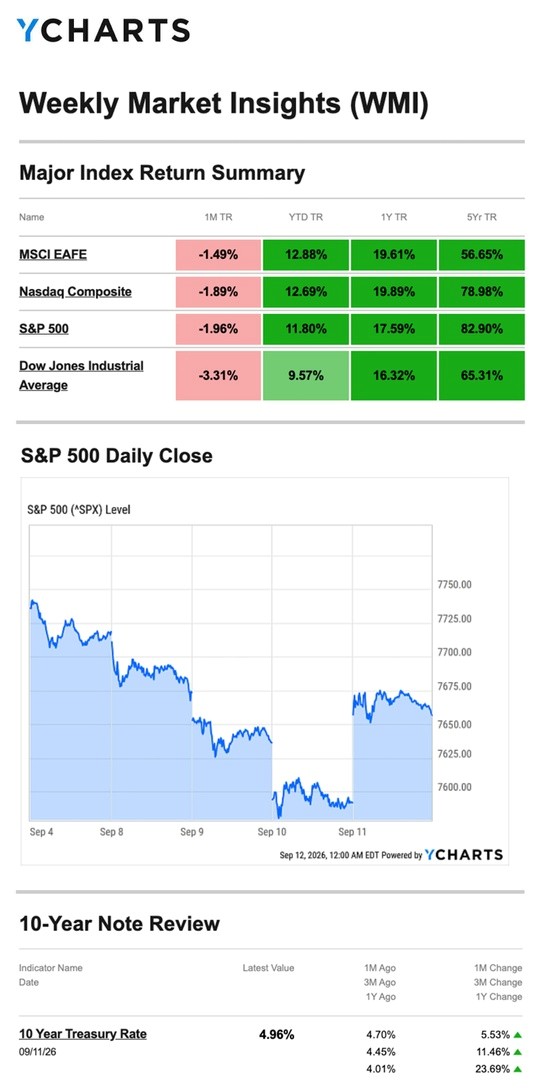
Stocks fell over a shortened trading week as higher oil prices rattled investors.
The Standard & Poor’s 500 Index declined 0.80 percent, while the Nasdaq Composite Index edged down 0.66 percent. The Dow Jones Industrial Average fell 1.57 percent. The MSCI EAFE Index, which tracks developed overseas stock markets, skidded 1.39 percent.1,2
Sluggish Start
Stocks fell in response to higher oil prices at Tuesday’s opening bell as investors returned from the long Labor Day weekend. Investors kept one eye on diplomatic efforts in the Middle East and another on fresh inflation reports due out later in the week.3
Stocks were under pressure again on Wednesday as oil prices continued climbing. After the Treasury Department announced it was tripling its long-dated debt buyback program (to as much as $6 billion), the yield on the 10-year Treasury note rose to a 3-year high. Investors continued to fret over inflation as the week progressed, putting further pressure on stocks.4,5
On Friday, stocks rebounded after news that annualized inflation held steady in August, puzzling some who expected stocks to decline. Oil prices fell, and markets rebounded to finish a tough week on an upbeat note.6
Inflation Reports
Wholesale inflation was released on Thursday; PPI, or the Producer Price Index, rose 0.4 percent in August over the prior month, in line with expectations. Stocks were under pressure despite the tame results.7
But on Friday, the latest CPI (Consumer Price Index) report showed that year-over-year retail inflation in August held steady at 3.4 percent. Traders appeared to look past the report, with the question shifting from whether the Fed will adjust rates this year to how many times the Fed may need to act.8
This Week: Key Economic Data
Tuesday: Federal Open Market Committee (FOMC) Meeting, Day 1.
Wednesday: Federal Open Market Committee (FOMC) Meeting, Day 2. Retail Sales. Import Prices. Manufacturing & Trade Inventories. NAHB Housing Market Index. Fed interest rate decision.
Thursday: Housing Starts. Weekly Jobless Claims. Pending Home Sales.
Friday: Industrial Production. Capacity Utilization. Leading Indicators.
Source: Investor’s Business Daily – Econoday economic calendar: September 11, 2026. The Econoday economic calendar lists upcoming U.S. economic data releases (including key economic indicators), Federal Reserve policy meetings, and speaking engagements of Federal Reserve officials. The content is developed from sources believed to provide accurate information. The forecasts or forward-looking statements are based on assumptions and may not materialize. The forecasts are also subject to revision.